A bank statement loan lets a self-employed borrower prove income with 12 or 24 months of deposits instead of tax returns. The lender adds up what came in, subtracts an estimate of business costs, and treats what’s left as monthly income. Expect a higher rate than a standard mortgage and a bigger down payment. In return, you can qualify even when write-offs make your tax return look thin.
Bank statement loan basics for self-employed borrowers
1. Deposits replace tax returns
A standard lender reads the bottom line of your tax return. If you wrote off a truck, a home office and half your phone bill, that bottom line looks small, even though plenty of money moved through your account. These programs read the deposits instead. They’re non-QM mortgages, so they sit outside the standard Qualified Mortgage rules and use their own guidelines.
2. Who it fits
Business owners, freelancers, gig workers and commission earners use them most. A bank statement loan usually asks for at least two years of self-employment, though some lenders accept less if you’ve worked in the same field for years. W-2 employees rarely need one.
How lenders turn deposits into income
1. Personal or business statements
Most programs accept personal statements, business statements, or a mix. Personal statements are simpler because the money already lands in your own account. Business statements show revenue, but the lender has to estimate how much of it you actually keep.
Why the expense factor matters
When a lender reads business deposits, it applies an expense factor. Some programs use a flat percentage, often around 50%. Others accept a letter from your CPA showing your real costs. This one setting can change your buying power more than a quarter point on the rate ever will.
2. Twelve months or twenty-four
A 12-month review shows your recent income, which helps if business is growing. A 24-month review smooths out spikes and dips, which can help if your deposits swing around. Does the longer window help you or hurt you? It depends on whether last year beat the year before, and only your statements can answer that. Ask for both calculations. A good loan officer will run them side by side.
3. What gets left out
Lenders usually strip out transfers between your own accounts, loan proceeds, refunds and one-time windfalls. Only real business or earned income counts. That’s why a messy account can shrink your number fast.
A worked example with $30,000 a month in deposits
These numbers are illustrations, not quotes. Real programs vary.
1. The deposits
Say your business account shows $360,000 in eligible deposits over 12 months, or $30,000 a month.
2. Two ways to count income
With a 50% expense factor, your qualifying income is $15,000 a month. With a CPA letter showing real expenses of 30%, a program that accepts it counts $21,000 a month. Same business, same deposits.
3. What that does to your budget
Suppose the lender allows a 43% debt-to-income ratio and you carry $1,000 a month in other debts. At $15,000, total debts can reach $6,450, which leaves about $5,450 for housing. At $21,000, they can reach $9,030, which leaves about $8,030. Take out $1,000 a month for taxes and insurance, and at an illustrative 7.5% rate on a 30-year fixed loan, the first case supports a loan of about $636,000. The second supports about $1 million. That’s a $364,000 gap from one input. Plug your own numbers into our mortgage calculators.
Bank statement loan rates today: what to expect
1. Rates sit above conventional
These programs usually price higher than standard mortgages, often by roughly half a point to two points. The extra cost pays for added risk and manual review.
2. What recent published numbers look like
Public rate sheets are all over the place. One lender’s sheet showed rates starting near 6.4% for a borrower with a 740 credit score at 75% loan-to-value, while another sample scenario with 25% down and a 739+ score came in near 7.5%. A weekly index put the observed range at about 7.0% to 7.5%. These are third-party examples from recent weeks, not Taylor Weiner Team quotes, and they’ll be out of date soon.
3. Why no single number is honest
Credit score, down payment, loan size, property type and statement type all move the rate. Anyone who promises one of the bank statement loan rates today to every borrower is guessing. The only useful number is the one quoted on your file, on the day you ask.
Costs beyond the rate
1. Down payment
Many programs ask for 10% to 25% or more, depending on your credit, the loan size and the property. Larger down payments often earn better pricing.
2. Cash reserves
Lenders often want savings left after closing. Several months of mortgage payments is common, and some programs ask for more.
3. Prepayment terms
Some programs include prepayment penalties, especially on investment properties. That means paying off the loan early, through a sale or a refinance, could cost you. Ask for the penalty terms in writing.
Documents to gather
1. The statements
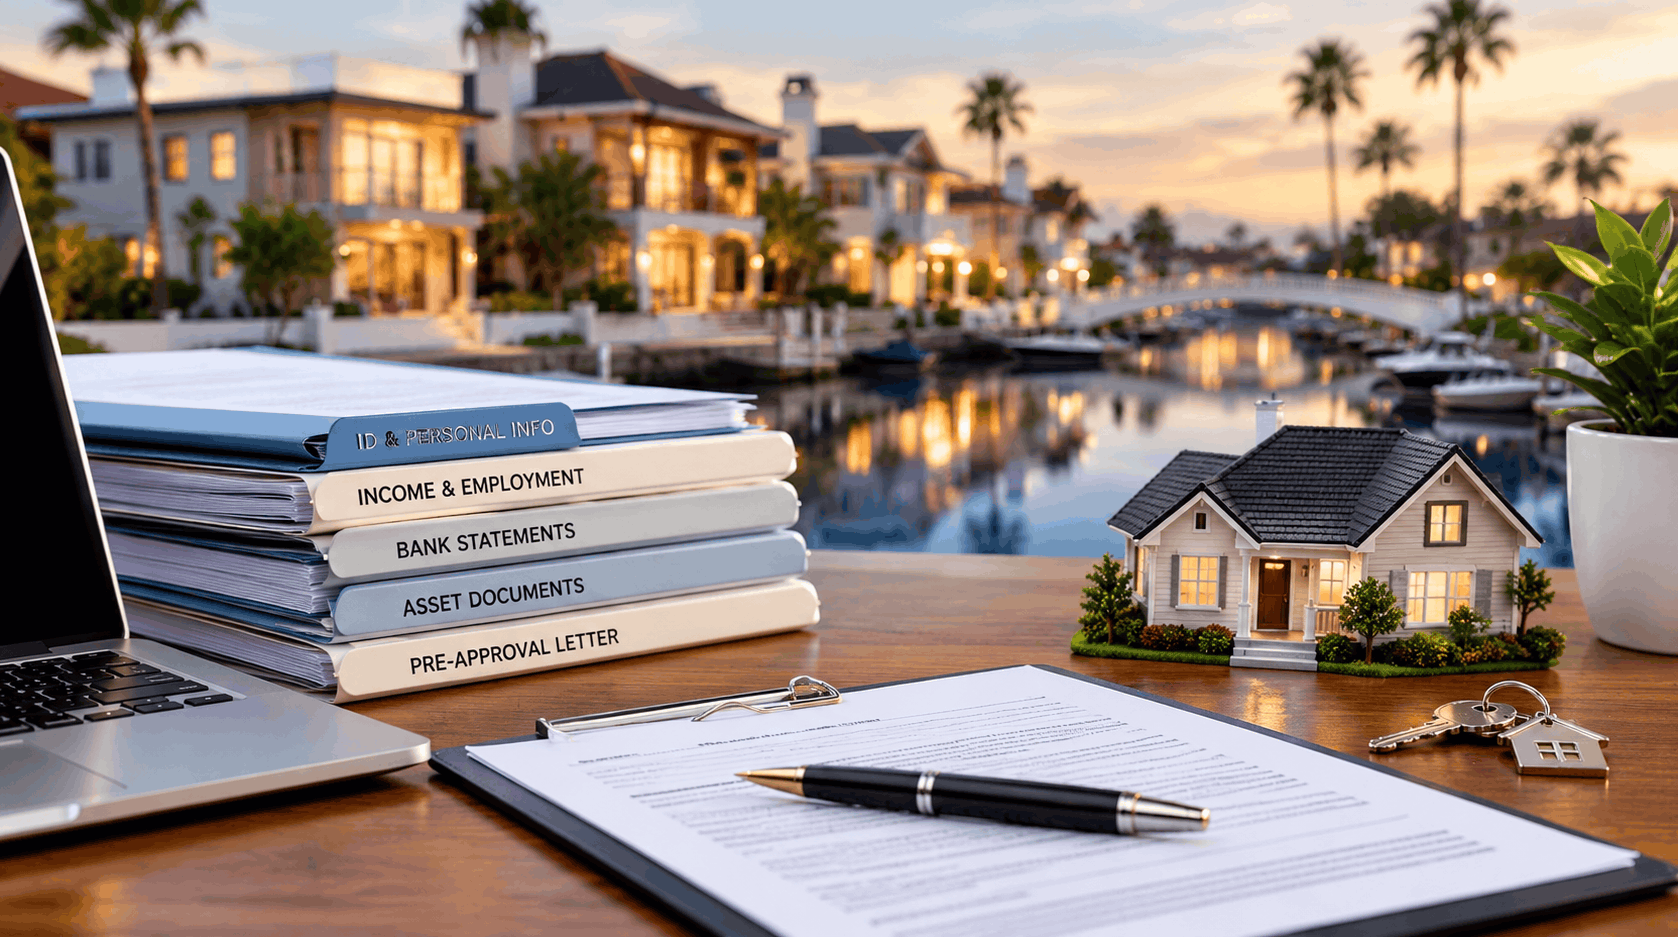
Pull 12 or 24 months of statements for each account you want counted. Send every page, including the ones that look empty. Missing pages stall more files than anything else.
2. A profit and loss statement or CPA letter
Some programs want a year-to-date profit and loss statement. Others take a CPA letter that confirms your business has operated for at least two years and states your expense ratio.
3. Proof your business is real
Expect to show a business license, a registration, or another record that proves you own the company. Add your photo ID and your usual credit and asset documents.
Mistakes that hurt approval
1. Mixing personal and business money
If your grocery runs and client payments share one account, the lender has to untangle them. Separate accounts make your income easier to read, and easier to approve.
2. Unexplained deposits
A big deposit with no paper trail raises questions. Keep invoices, contracts or transfer records for anything unusual.
3. Shopping on rate alone
Ask how each lender counts your deposits before you compare rates. A low rate on a stingy income calculation can leave you with a smaller loan than a slightly higher rate on a fair one. You can see how the Taylor Weiner Team handles non-QM programs before you decide.
Conclusion
1. Your next step
A bank statement loan lets your deposits do the talking when your tax returns can’t. Gather clean statements, keep business and personal money apart, and ask each lender how they count income and what they charge. Get a real quote instead of chasing bank statement loan rates today in a search box. Taylor Weiner has 20 years of mortgage experience, a 5.0 rating on Google, and 450+ five-star reviews.
FAQs
1. How many months of statements do I need?
Most programs ask for 12 or 24 months, depending on the lender and your income pattern.
2. Can I use personal or business statements?
Often either, and some programs allow a mix.
3. What are typical bank statement loan rates today?
They change daily and depend on your file, but they usually run above conventional rates. Ask for a quote on your numbers.
4. How much down payment do I need?
Many programs ask for 10% to 25% or more, depending on credit and loan size.
5. Can I refinance into a standard mortgage later?
Often yes, once you qualify for a standard loan. Check for prepayment penalties first.