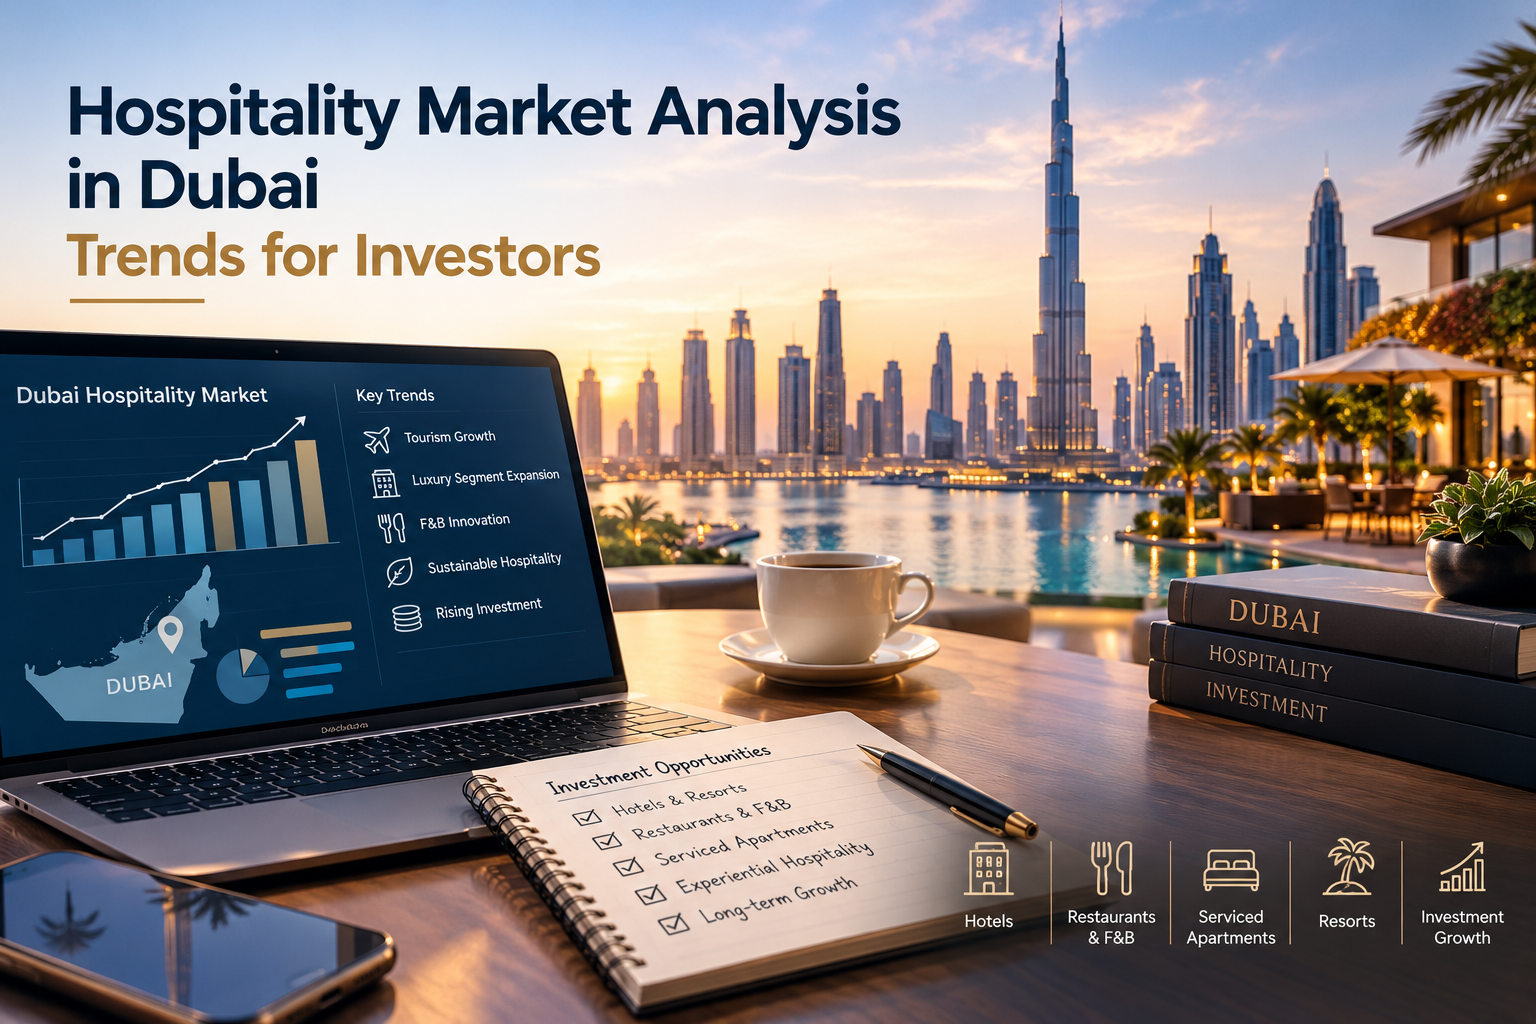
Dubai’s hospitality sector is entering a more selective phase as tourism growth meets new supply and regional volatility. Hospitality market analysis in Dubai shows 19.59 million international visitors in 2025, while hotel occupancy fell to 36% in March 2026 before recovering to 66% by August.
For investors, these shifts make demand, location, supply, and hotel performance key factors when assessing opportunities. Reviewing Dubai hospitality market trends can help investors identify where demand is strengthening and which factors may affect hotel performance.
Dubai Hospitality Market Snapshot
Dubai’s recent performance provides a useful baseline for understanding demand, hotel supply, and investment conditions.
Hospitality Market Analysis Trends in Dubai: The Baseline
The year set a strong benchmark for the sector. Hotel occupancy averaged about 81%, while Dubai added roughly 3,400 rooms, increasing inventory by 2.2%.
Key indicators include:
- Tourism statistics: 19.59 million international overnight visitors
- Largest source market: Western Europe, at about 21% of arrivals
- Inventory mix: Nearly 7 in 10 hotels sit in the upscale, upper-upscale, and luxury categories
- UAE-wide performance: RevPAR and ADR rose 11.9% year on year through August, with occupancy at 78.5%
The 2026 Disruption and Recovery
The first half of 2026 tested the Dubai hospitality market. H1 occupancy averaged 56.4%, and ADR fell 7% to AED 701. Hotels largely held rates instead of discounting heavily.
Demand has since rebuilt. Dubai recorded 6.97 million visitors from January to August, plus 21.61 million occupied room nights. August alone brought 869,000 visitors, the strongest month since February.
Dubai Hotel Market Analysis: Supply and Performance
Performance varies by segment and location, making citywide averages less useful for investors.
Segment and Location Performance
Upper-midscale hotels recorded 65.7% occupancy, while mid-range hotel apartments reached 73%. Downtown Dubai, DIFC, and Palm Jumeirah reportedly exceeded 80% as summer eased.
Pipeline and Branded Residences
As of August 2026, the market had 794 hotel establishments and 148,796 rooms. New projects remain active, including Azizi Developments’ first five-star hotel and Ritz-Carlton Residences at The World Islands.
UAE Hospitality Market Analysis: Where Capital Is Moving
Capital is moving toward assets with stronger operating potential, while public-sector investment continues to support long-term hospitality demand.
Acquisitions and Repositioning
Investor interest has shifted toward acquisitions, repositioning, and operational upgrades. Dubai accounted for 55.9% of the UAE’s upcoming hotel supply.
Market uncertainty has slowed deals, but activity has not stopped. Some transactions have been delayed rather than cancelled, while investors continue to assess yields against borrowing costs.
Government and Sovereign Capital
Investment Corporation of Dubai plans to reinvest in local properties over the next six to 12 months, with hospitality and leisure representing 17% of its portfolio. Dubai’s D33 agenda also supports long-term tourism and economic growth.
Dubai Hospitality Market Research Insights: Why F&B Matters
Room revenue is only part of hotel performance. Restaurants, lounges, and events can influence guest satisfaction, ancillary revenue, and overall asset value.
Why Food and Beverage Matters
F&B performance can affect reviews, repeat visits, and non-room revenue, making operational efficiency worth assessing alongside RevPAR. Finisya supports hospitality businesses across the UAE with insights into concept fit, efficiency, and profitability.
Operational Signals Investors Should Check
- Concept fit with the guest profile and location
- Menu engineering and food cost control
- Staffing flexibility during seasonal changes
- F&B revenue from hotel guests versus outside visitors
- Dining-related guest feedback
Hotel Industry Growth Analysis in Dubai: Risks and Outlook
The outlook remains positive, but recovery depends on travel connectivity, supply absorption, and how individual assets manage changing demand.
Cavendish Maxwell expects 2026 occupancy at 60.4%–66.2%, with ADR of AED 600–675.
Key risks:
- Geopolitical shocks affecting air connectivity
- Growing luxury supply
- Margin pressure from discounting
- Dependence on limited source markets
Longer-term support comes from Dubai’s airport capacity, diverse visitor base, and continued infrastructure investment.
Investor Checklist
Before investing, assess:
- Occupancy, ADR, and RevPAR by segment and location
- Performance under a shock scenario such as H1 2026
- ADR recovery after disruption
- F&B concept and operating model
- Data sources and hotel inventory definitions
FAQs
- Why does hotel location matter when assessing a Dubai hospitality investment?
Location affects access to business districts, attractions, transport, and target guests, which can influence occupancy and room rates. - How can investors assess whether new hotel supply is a risk?
Review upcoming rooms within the same segment and micro-location, then compare them with expected demand growth and existing hotel performance. - What role does F&B play in hotel investment decisions?
A strong F&B operation can generate additional revenue, attract outside visitors, and strengthen the property’s overall guest experience. - How should investors assess a hotel during market uncertainty?
Test the asset against lower occupancy, weaker ADR, delayed recovery, and higher operating costs rather than relying only on base-case forecasts. - Which data should be verified before making a hospitality investment?
Check the source, reporting period, inventory definition, occupancy, ADR, RevPAR, upcoming supply, and assumptions behind any market forecast.